Guide
The 50/30/20 budget rule, explained with examples
Split your take-home pay into 50% needs, 30% wants and 20% savings — the simplest budgeting framework that actually works, plus when to bend it.
By MoneyHabit Editorial Team · 17 October 2026 · 6 min read
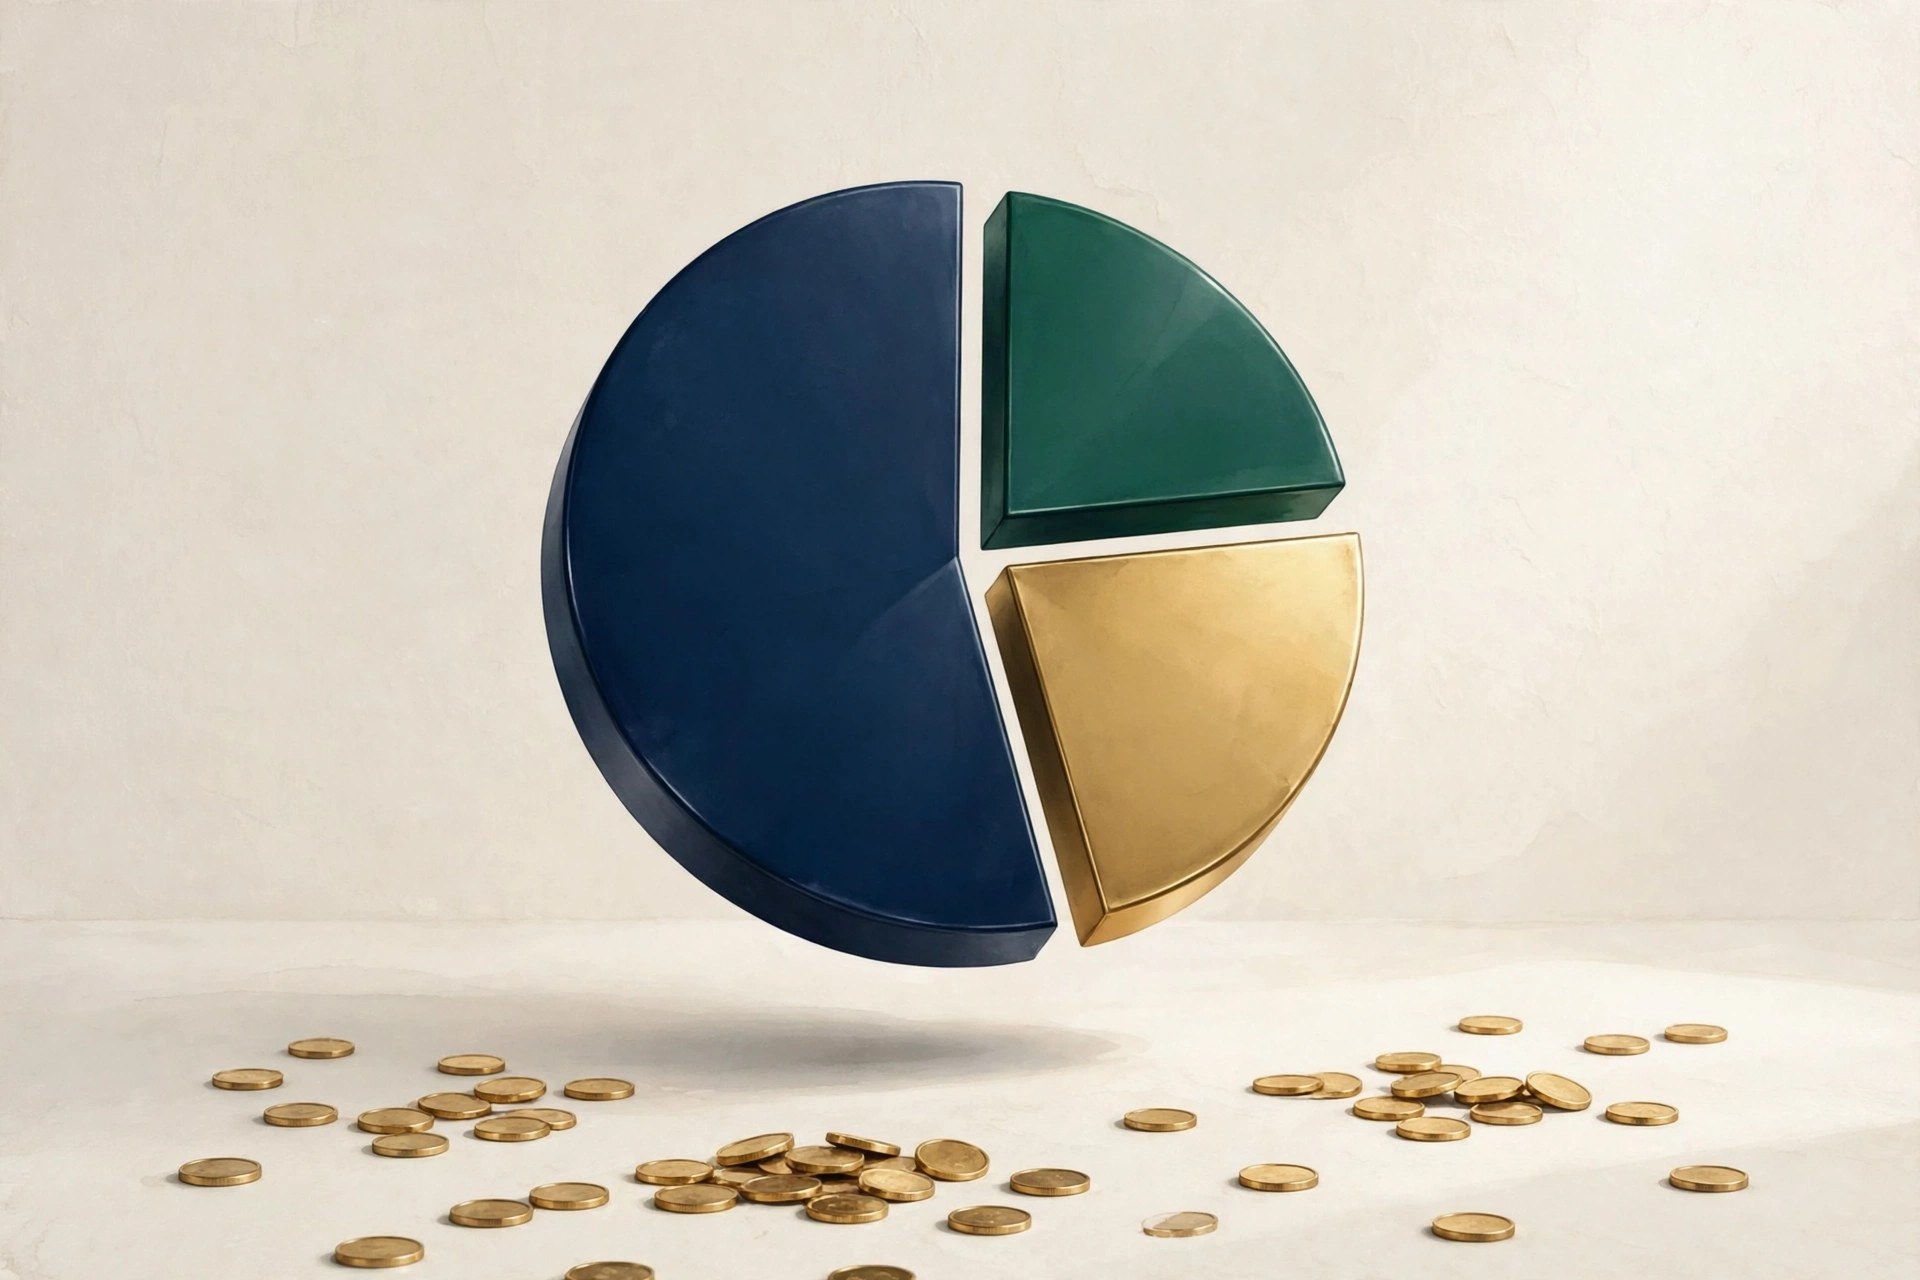
Most budgets fail for a simple reason: they ask too much. Dozens of categories, every receipt logged, a spreadsheet that becomes a second job. The 50/30/20 rule takes the opposite approach. It splits your take-home pay into just three buckets — 50% for needs, 30% for wants, 20% for savings and debt — and that is the whole system.
Popularised by Elizabeth Warren and Amelia Warren Tyagi in their 2005 book All Your Worth, the rule has survived two decades because it replaces budgeting homework with one clear picture of where your money goes. Here is how it works, where it shines, and when to bend it.
What the 50/30/20 rule actually says
Take your after-tax income — the money that actually lands in your account, not your salary figure — and divide it three ways:
| Bucket | Share | What goes in it |
|---|---|---|
| Needs | 50% | Housing, utilities, groceries, transport to work, insurance, minimum debt payments |
| Wants | 30% | Dining out, streaming, hobbies, holidays, non-essential shopping |
| Savings & debt | 20% | Emergency fund, retirement, investments, extra debt payments above the minimum |
The test for "need versus want" is practical: a need is something you would keep paying for even if your income dropped tomorrow. Your rent is a need. The premium streaming bundle is a want. Minimum credit-card payments are a need; anything above the minimum belongs in the 20% bucket.
The 50/30/20 rule is a starting ratio, not a rigid cap. Its job is to show you the shape of your spending — then you decide what to change.
A worked example
Say your take-home pay is £2,000 a month:
- Needs (50%): £1,000 for rent, bills, groceries, commuting and minimum debt payments
- Wants (30%): £600 for eating out, entertainment, hobbies and treats
- Savings & debt (20%): £400 straight to savings or extra debt payments
Notice what the rule does not ask: it does not care whether you spent £42 or £47 on groceries last Tuesday. It only asks whether each bucket roughly holds its shape at month's end.
How to start in three steps
1. Find your real number
Add up what actually hits your bank account each month after tax and deductions. If you are paid biweekly, multiply one paycheque by 26 and divide by 12. Everything flows from this number.
2. Sort last month into three buckets
Pull up last month's bank statement and label every outgoing as need, want, or savings. Most people discover two things: the wants bucket is bigger than they thought, and the savings bucket is mostly empty. That diagnosis is exactly what the rule is for.
3. Pay yourself first
On payday, move the 20% into a separate savings account before you spend anything. Automation beats willpower — money you never see is money you never miss.
Make the 20% automatic. Set up a standing order or automatic transfer for payday. If saving relies on what is "left over" at month's end, there rarely is any.
When to bend the rule
The rule's honesty is also its limit: real life does not always fit 50/30/20. Bend it deliberately rather than abandoning it:
- High-cost area: if rent alone eats 45% of your income, try 60/20/20 or even 75/15/10 for a while. Keeping some savings rate matters more than hitting exact percentages.
- Heavy high-interest debt: flip to 50/20/30 while you attack the balances — shrinking the wants bucket temporarily saves far more in interest than it costs in fun.
- High income: the percentages do not scale forever. Nobody needs 30% of a very large income for wants; bank the surplus into savings instead.
- Irregular income: base the buckets on your lowest typical month, and allocate windfalls by priority rather than by percentage.
Watch the debt trap. If you are carrying high-interest credit card debt, putting a full 30% toward wants while paying only minimums can cost thousands in extra interest. In debt-payoff mode, the wants bucket is the first thing to shrink.
Frequently asked questions
Is it 50/30/20 of gross or net income?
Net — your take-home pay after tax and deductions. Using gross pay makes every bucket look healthier than it is.
What counts as savings in the 20%?
Emergency fund contributions, retirement savings, investments, and any debt payments above the minimum. Minimum debt payments are a need; extra payments are savings.
Can couples use one 50/30/20 budget?
Yes — many couples find it easier to agree on three buckets than on fifty line items. Agree the shape first, then divide the detail.
What if my needs are already over 50%?
You are not failing; the rule is revealing pressure. Use an adjusted split like 60/20/20, protect at least some savings, and revisit when income rises or big fixed costs change.
Is 20% enough for retirement?
Often not on its own — many advisers suggest around 15% of income for retirement alone. Treat 20% as a floor for total savings and debt payoff, not a ceiling.
Key takeaways
- Split take-home pay into 50% needs, 30% wants, 20% savings and debt.
- Use it as a starting ratio and adjust for your city, debt, and income.
- Automate the 20% on payday — pay yourself first.
- Shrink wants before savings when attacking high-interest debt.
The 50/30/20 rule will not make you rich by itself. What it does is harder and more valuable: it gives you a clear, honest picture of your money in about ten minutes a month — and a picture you can actually act on.
Sources
More in Budgeting & Saving
Budgeting & Saving · Guide
How to build an emergency fund on a tight budget
You don't need three months of expenses saved before an emergency fund helps. Here's a step-by-step plan to build your first $500–$1,000 safety net on a tight budget — and grow it from there.
17 October 2026 · 10 min read
Budgeting & Saving · Guide
The two-account budget: a simpler way to stop overspending
Separate what you must pay from what you may spend, and most budgeting decisions make themselves.
10 October 2026 · 6 min read