Guide
CD vs High-Yield Savings: Which Wins Now?
CDs pay up to 5.25% but lock your cash away; high-yield savings pays up to 5.00% and stays flexible. Here is how to pick a winner after the Fed rate hike.
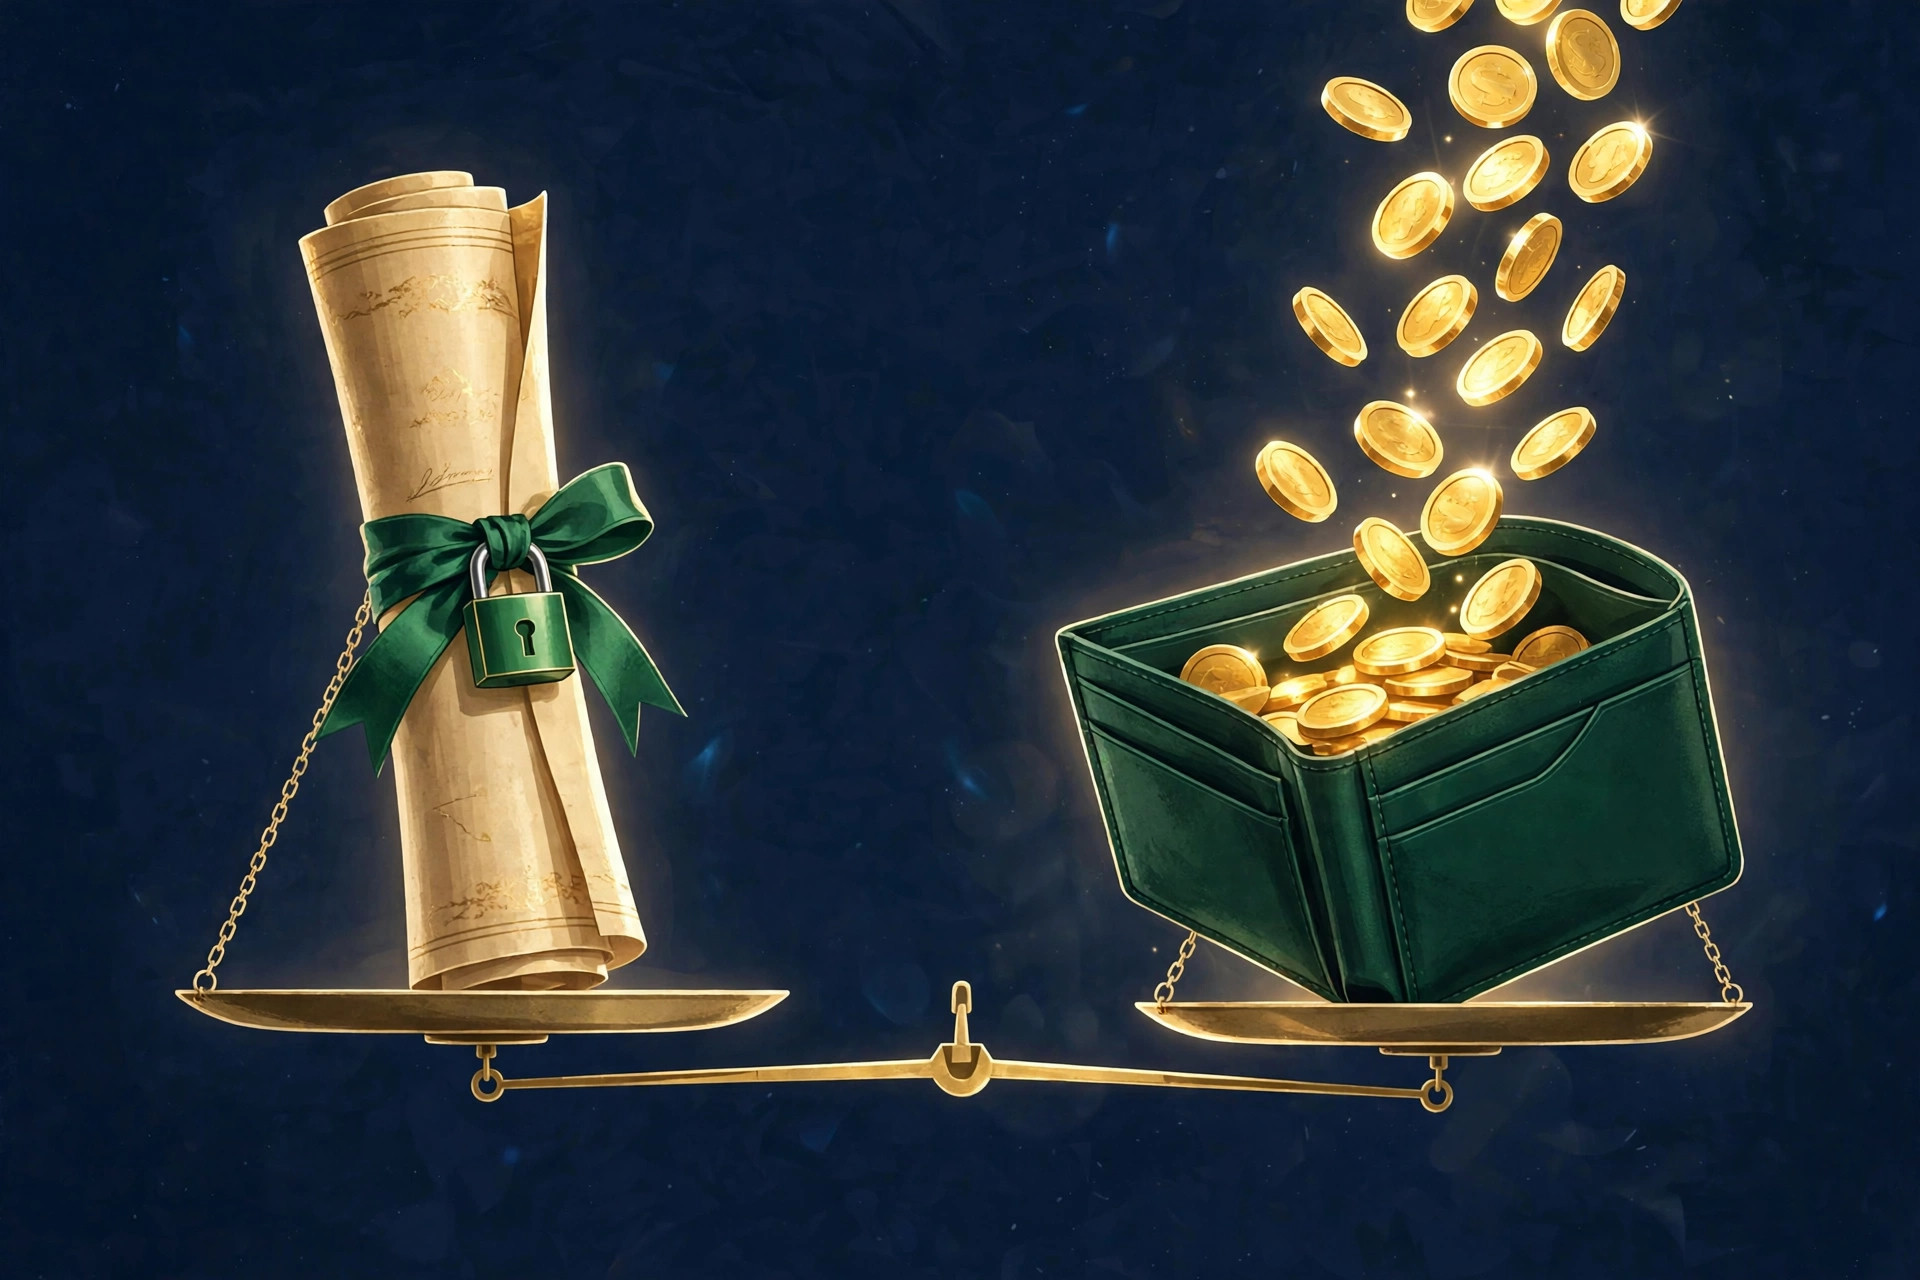
Since the Federal Reserve raised rates on September 16, 2026 — to 3.75–4.00%, its first hike since 2023 — savers have a new kind of good problem. Certificate of deposit (CD) rates now reach 5.25% APY, while the best high-yield savings accounts pay 5.00% APY. A widely-shared Q&A video this week asked the question on everyone's mind: can you actually make more money by locking cash into a CD? The honest answer is "it depends" — and the reasoning matters more than the headline rate.
Here is how the two options compare right now, where the Fed's move actually lands, and a simple rule for choosing.
What each one actually is
A certificate of deposit (CD) locks your money away for a fixed term — three months, a year, five years — in exchange for a guaranteed rate for the whole period. Withdraw early and you pay an early withdrawal penalty, usually several months' interest.
A high-yield savings account (HYSA) pays an elevated but variable rate with full liquidity — you can add or withdraw money anytime. The rate can change at any moment because it tracks market rates and the Fed.
Both are insured up to $250,000 per depositor per institution (FDIC for banks, NCUA for credit unions), so safety is a wash. The real trade-off is rate certainty versus flexibility.
The best rates right now (late October 2026)
Rates move fast — always compare fresh quotes before opening anything. This week, per the Wall Street Journal's October 20–22 rate surveys:
| Product | Best rates seen | National average |
|---|---|---|
| Certificates of deposit | 4.35%–5.25% APY; standouts include Tower Federal Credit Union at 5.20% (24 months, $500 minimum) and Toyota Financial Savings Bank at 5.25% (60 months, $1 minimum) | 1.76% for a 12-month CD (FDIC); top-tier high-yield CDs averaged 4.79% (DepositAccounts.com) |
| High-yield savings | Up to 5.00% APY — Axos Bank leads, though it requires $1,500 in a linked checking account plus $1,500 in monthly direct deposits; GO2bank pays 4.50% on balances up to $5,000 | 0.38% (FDIC); the top 1% of savings accounts averaged 4.04% (DepositAccounts.com) |
The best CDs do beat the best savings accounts right now — 5.25% versus 5.00%. But the averages are shockingly low by comparison: 1.76% versus 4.79% for CDs, 0.38% versus 5.00% for savings.
The rate-gap rule: before choosing between a CD and savings, check what your current account pays. Moving from a 0.38% average account to a 4.50%+ high-yield one is usually a bigger win than the CD-versus-savings debate itself.
Where the Fed's hike actually lands
After three cuts in 2025 and five steady meetings in 2026, the Fed hiked in September on surging energy prices, with most officials penciling in one more increase before year-end. The next meeting is October 27–28. How that flows through: high-yield savings rates respond quickly — they're variable, so they follow the Fed toward 5.00% and would climb further on a December hike (or drift down if cuts return). CD rates are about expectations, not the present — banks set them on where they think rates are headed. The fact that longer-term CDs (5.10%–5.25% at 36–60 months) slightly outpay short ones suggests banks want your money locked in now.
The top CD pays 5.25% today; the top savings account pays 5.00% — but savings can follow the Fed higher, while the CD rate is frozen the day you buy. Which advantage wins depends on what happens next.
When a CD is the better choice
- You want to lock in today's rate. If you believe rates have peaked — or that cuts arrive in 2027 — a multi-year CD at 5.10%–5.25% freezes today's yield while HYSA rates would fall.
- The money has a date, not a doubt. A wedding next December, an April tax bill, a planned deposit — money with a fixed purpose and timing is ideal CD material.
- You want a commitment device. The early withdrawal penalty keeps your hands off money you'd otherwise impulse-spend.
The ladder: the middle ground
A CD ladder splits money across CDs with staggered maturities — say four CDs maturing in 6, 12, 18 and 24 months. One matures every few months, giving you regular access to a chunk of cash plus interest while the rest keeps earning. Reinvest each maturing rung at the longest term and the ladder rolls on. Watch the minimums, though: some of the best rates need $5,000–$10,000 per CD.
When high-yield savings is the better choice
- Your emergency fund. Instant access is the whole point; a CD's early withdrawal penalty directly conflicts with it. A HYSA paying 4.50%+ does the job.
- Your plans are uncertain. Moving house, job hunting, irregular income — if you can't promise the money won't be needed, don't lock it up.
- You want to ride rising rates. If the Fed hikes again in December, HYSA rates climb with it while your CD sits still. In a rising-rate environment, liquidity has real option value.
Watch the hoops. That headline 5.00% requires a $1,500 checking balance and $1,500 in monthly direct deposits — miss a condition and the rate drops. A simple no-hoops account near 4.27%–4.40% often beats a high-maintenance headline rate in real life. Read the conditions, not just the big number.
A quick note for UK readers
The same debate exists under different names: fixed-rate bonds (the UK's CD equivalent) versus easy-access savings. Fixed bonds were nearing 5.37% AER against roughly 5.00% AER easy access in late October — a similarly tight gap. One structural difference: UK savings are protected by the Financial Services Compensation Scheme up to £85,000 per institution.
The 3-question rule
- When do I need the money? Emergency or uncertain → savings. Fixed date, no early need → CD.
- What do I believe about future rates? If rates fall from here, lock a CD. If the Fed hikes again in December, savings captures it automatically.
- Is my current account already near the top? Moving from an average account (1.76% CD / 0.38% savings) to a best-in-class one is the biggest single win, whichever product you choose.
Frequently asked questions
Can I lose money in a CD?
Principal is insured up to $250,000 per depositor per institution and the rate is guaranteed — no market losses. The real risk is an early withdrawal penalty, which can eat months of interest and, if you withdraw very early, dip slightly into principal.
Should I lock in a CD before the October 27–28 Fed meeting?
For long terms, probably not — if the Fed hikes again in December, CD rates will likely rise further. Short-term CDs (3–6 months) or a ladder let you lock something in now and reassess later. Flexible savings captures any hike automatically.
Are no-penalty CDs worth it?
They split the difference: a CD rate with the option to withdraw after an initial period (usually 6–10 days) with no fee. Their rates run below standard CDs but well above average savings accounts — a genuine compromise if commitment makes you nervous.
Key takeaways
- Top CDs pay up to 5.25% APY; top high-yield savings reaches 5.00% — but national averages are far lower (1.76% and 0.38%), so shopping around is the biggest win.
- CDs guarantee a rate; high-yield savings stays flexible and tracks the Fed. The right choice depends on when you'll need the money and where you think rates go next.
- Emergency funds and uncertain plans belong in flexible savings; money with a fixed purpose and date is ideal CD material.
- A CD ladder blends high locked-in yields with regularly opening liquidity windows — a strong middle ground.
- If the Fed hikes again in December, savings rates will likely follow; locking a long CD now is a bet that rates have peaked.
Bottom line: this isn't a contest with one winner. Many savers do best with both — a flexible high-yield account for emergencies and a CD or two for dated goals. Your next step is a ten-minute audit: check what your current accounts pay against the best offers above, and move anything earning near the national average before the October 27–28 Fed meeting.
Sources
More in Budgeting & Saving
Budgeting & Saving · Guide
Holiday Spending Plan: Enjoy December, Not Debt
A practical plan to cover gifts, food, travel and the long January pay gap — so December's fun doesn't become January's debt.
22 October 2026 · 7 min read
Budgeting & Saving · Guide
One Month Ahead: Escape the Paycheck-to-Paycheck Cycle
Paycheck-to-paycheck living is often a timing problem, not an income problem. Here is the viral one-month bill buffer method, step by step.
21 October 2026 · 6 min read
Budgeting & Saving · Habit
Is Your Spare Cash Working Hard Enough?
Three in four savers say their spare cash isn't pulling its weight. A new survey explains why — and here's a five-step habit to close the gap.
20 October 2026 · 6 min read