News
Caring for Aging Parents: What It Really Costs in 2026
Family caregivers now spend $11,508 a year out of pocket — up 59% in five years. Here's where the money goes and how to plan before a crisis decides for you.
In this article
- What caregivers actually spend
- The costs that never show up on a bill
- What professional care costs in 2025
- What Medicare and Medicaid actually pay for
- The giveaway trap: when a parent starts handing money away
- The $5,000 credit that is not law yet
- How to plan before the crisis
- Frequently asked questions
- Key takeaways
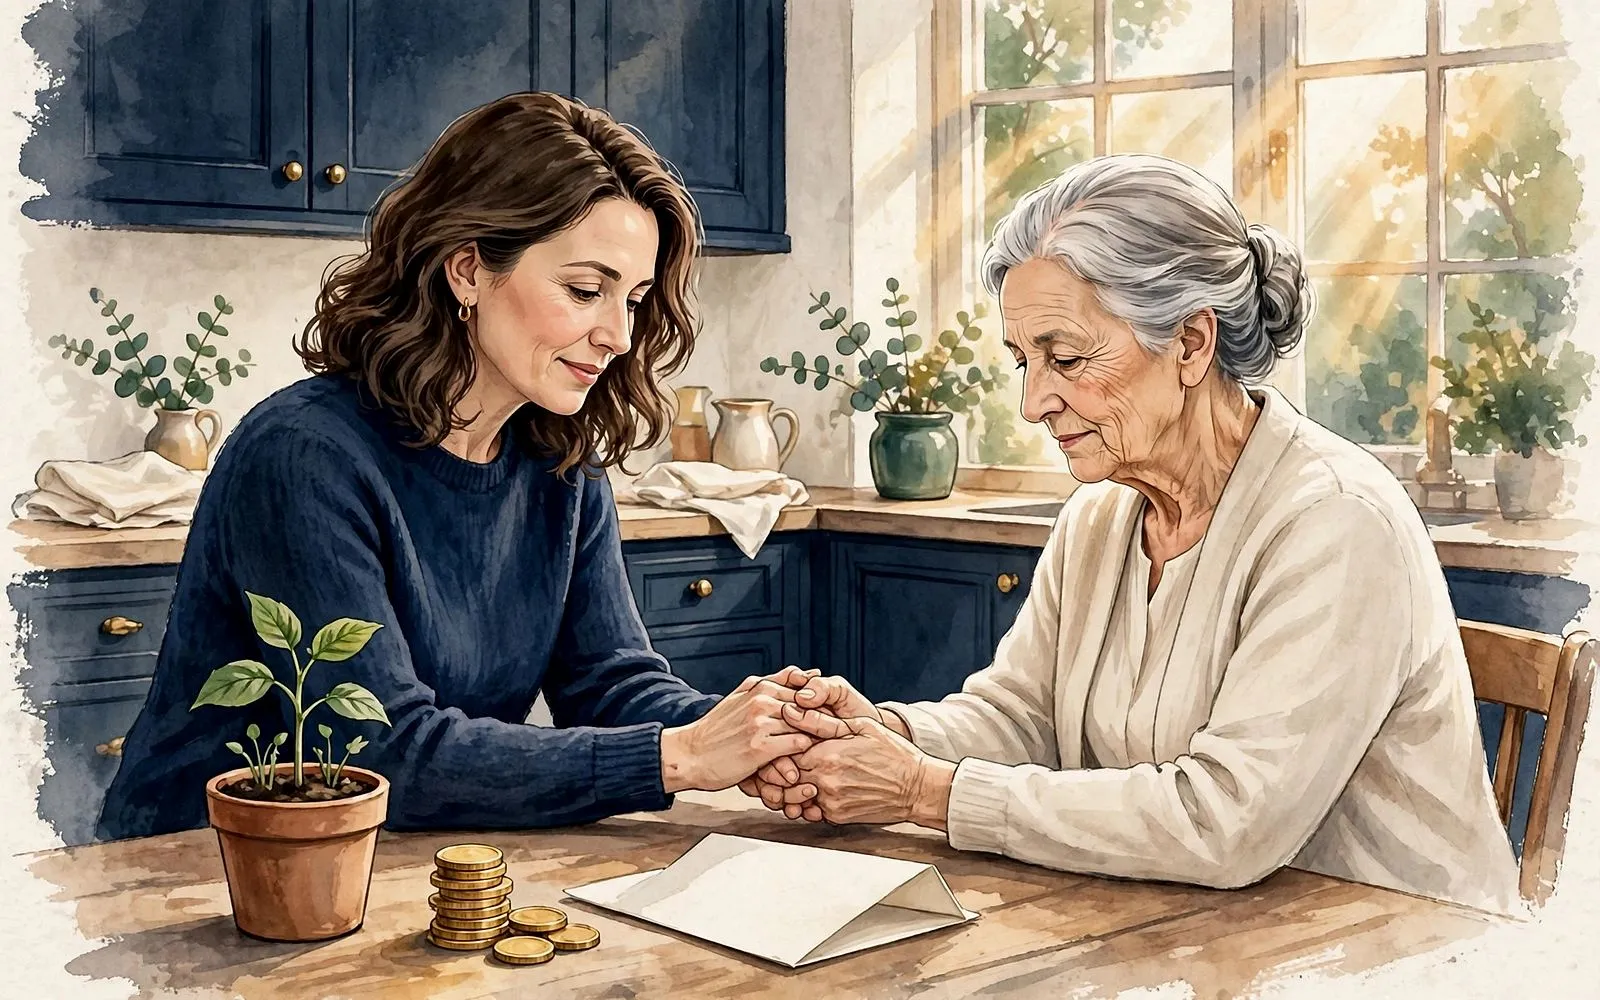
November is National Family Caregivers Month, and this year it arrives with a number that should stop every family in its tracks: $11,508 a year. That is what the average family caregiver now spends out of pocket caring for an aging parent or loved one, according to a new AARP report released on 28 October 2026 — up 59% from $7,242 just five years ago. The same week, a viral Ramsey Show clip showed the other side: an 82-year-old widow who, five months after her husband died, had given away nearly all of her savings — $700,000 to $1 million. The cost of caring for aging parents is rising fast, and families that do not plan for it pay for it anyway — usually at the worst possible moment.
AARP counts roughly 63 million family caregivers in the United States — most untrained, unpaid, and paying out of pocket while holding down their own jobs. Here is what the care really costs in 2026, what Medicare and Medicaid actually cover, the trap that can wipe out a parent's savings, and how to plan before a crisis decides for you.
What caregivers actually spend
AARP's 2026 Caregiving Out-of-Pocket Costs Study surveyed 2,538 family caregivers, who tracked spending in a one-week diary during June and July 2026. The headline figure — $11,508 a year, about $959 a month — is an average that hides how unevenly the burden falls. Nearly nine in ten caregivers incur expenses, and caregiving consumes 31% of household income on average. For households earning under $40,000 a year, the dollar spend is nearly as high — $11,448 — but it eats 76% of household income.
| Where the money goes | Average per year | Share of spending |
|---|---|---|
| Housing and household costs (rent or mortgage help, utilities, groceries, supplies, home modifications) | $4,797 | 42% |
| Medical costs (co-pays, prescriptions, equipment) | $3,313 | 29% |
| Everything else (transport, respite care, legal costs) | About $3,400 | About 29% |
The biggest expense is not medical care — it is the day-to-day infrastructure of another person's life: lights, food, and a safe home. Dementia makes it worse: $15,846 a year on average, against $10,221 without dementia.
"New findings underscore the need for tax credits and other financial relief for America's 63 million family caregivers."
— AARP, announcing the 2026 Caregiving Out-of-Pocket Costs Study
The costs that never show up on a bill
The $11,508 is only what caregivers can itemise. The bigger cost is time. AARP's separate Valuing the Invaluable 2026 report estimates that 59 million unpaid family caregivers provided care worth more than $1 trillion in 2024, at $20.41 an hour. The average caregiver gives about 27 hours a week — care that would cost closer to $49,000 a year at agency prices.
Those hours come out of somewhere. Caregivers cut back working hours, turn down promotions, retire early, or leave the workforce altogether — shrinking their own retirement savings, Social Security record, and emergency fund.
The first step costs nothing: sit down with your parent — and your siblings — and ask three questions before any crisis forces the conversation. What care do you want, and where? What money is available to pay for it? And who is authorised to act if you cannot?
What professional care costs in 2025
When family care is not enough, the professional alternatives shock most families the first time they look. CareScout's 2025 Cost of Care Survey (March 2026, 25,000+ provider rates across all 50 states) gives the national medians:
| Type of care | National median, 2025 |
|---|---|
| Non-medical home caregiver, 44 hours a week ($35/hour) | $80,080 a year |
| Assisted living community (private, one-bedroom) | $74,400 a year ($6,200 a month) |
| Nursing home, semi-private room ($315 a day) | $114,975 a year |
| Nursing home, private room ($355 a day) | $129,575 a year |
| Adult day health care | About $26,000 a year |
A single year in a private nursing home room costs more than the median American household earns in a year. If the 59 million unpaid caregivers stopped tomorrow, the formal care system could not absorb the demand.
What Medicare and Medicaid actually pay for
The most dangerous assumption in eldercare planning is that Medicare will handle it. It will not. Medicare covers hospital stays and short-term skilled nursing after a hospital stay — typically up to 100 days, and only for rehabilitation. It does not pay for routine help: no home aide, no assisted living, no long-term nursing home stay. Families who discover this in a hospital discharge meeting have days — sometimes hours — to find a solution.
Medicaid is the programme that does pay for long-term care, and it is the largest payer of these services in the country. But Medicaid is means-tested: in most states a single person must have very little income and very few countable assets — often around $2,000 — before it will pay. Many families face a "spend-down": paying privately at $6,000 to $11,000 a month until the parent's savings are nearly gone. One more rule catches families out. Medicaid has a five-year lookback: when someone applies, the state examines asset transfers made in the previous five years, and gifts given during that window can trigger a penalty period with no coverage — even if the money is long gone. That is how a well-meaning parent giving away savings can accidentally destroy their own safety net.
Do not give away assets to "qualify" for Medicaid without an elder law attorney. Transfers inside the five-year lookback can trigger a penalty period with no coverage at all, and the rules vary by state. A one-hour consultation usually costs a few hundred dollars; a mistaken gift can cost tens of thousands.
The giveaway trap: when a parent starts handing money away
An 82-year-old woman, healthy and active, lost her husband five months earlier, sold her home, moved to Tennessee to be near her daughter — and then began distributing nearly all of her life savings. Her daughter-in-law called The Ramsey Show worried about what happens when the money runs out. The clip went viral because almost every family recognises it: some saw a grieving widow giving away her own money; others saw possible early dementia, depression, or elder abuse, and urged a medical evaluation.
All of those reactions can be true at once. A parent's money is their money, and an adult child has no right to control it. But a sudden change in financial behaviour after a major loss deserves a calm, direct conversation — not an accusation, and not silence. Talk formally, with all siblings present. State the plain arithmetic: at $8,000 to $15,000 a month for assisted living, how long does the remaining money last? Ask what is driving the giving — generosity, guilt, loneliness, or pressure — because the answer changes the response. Get a medical check: a sudden change in money behaviour can be grief, depression, or an early sign of cognitive decline. And sort the paperwork — durable power of attorney, healthcare proxy, advance directive and an up-to-date will — which are almost impossible to arrange after capacity is lost. If the giving has already happened, see an elder law attorney: some transfers can be undone and some situations qualify for hardship exceptions.
The $5,000 credit that is not law yet
The Credit for Caring Act (H.R. 2036 / S. 925, reintroduced March 2025) would give working family caregivers a non-refundable tax credit worth 30% of qualifying caregiving expenses above $2,000, up to $5,000 a year. To qualify, a caregiver would need earned income above $7,500, and the person receiving care would need certified long-term care needs lasting at least 180 consecutive days. The credit would phase out above $150,000 of income for joint filers, or $75,000 for others. The bipartisan House Problem Solvers Caucus endorsed the bill on 22 October 2026.
But here is the part that matters: the bill is not law, and it has not passed in any Congress since it was first introduced in 2016. There is nothing to claim on a tax return. Anyone telling you otherwise is wrong. What you can claim now: the Child and Dependent Care Credit (20% to 35% of qualifying expenses if you pay for care for a qualifying person, including a parent who lives with you for more than half the year, so you can work); a dependent care FSA through your employer; a health savings account, which can cover some medical costs for a dependent parent; state programmes (Oklahoma's Caring for Caregivers Act, in effect since 2023, offers up to $3,000 a year — check your own state's revenue department); and Medicaid self-directed care, which in many states pays a family member for providing home care.
How to plan before the crisis
Eldercare planning fails when families never start, or start with the wrong question. The wrong question is "how much will it cost?" — nobody knows how long care will be needed. The right question is "what would we do if Mum fell tomorrow?" Work backwards from that. Map the money: list every income source and every regular expense. Check the insurance: long-term care cover, a hybrid life policy with a care rider, or veterans' benefits? Make the home safer, cheaply: grab bars, better lighting and fewer trip hazards can delay paid care by months or years. Use the free help: every US county has an Area Agency on Aging, and the National Family Caregiver Support Program funds respite care.
Frequently asked questions
How much does caring for an aging parent actually cost?
AARP's 2026 study puts the average at $11,508 a year out of pocket, or about $959 a month — 31% of the average caregiver's household income. Professional care costs far more: home aide $80,080 a year, assisted living $74,400, private nursing home room $129,575 (2025 medians).
Does Medicare pay for a nursing home?
Only briefly, and only for rehabilitation after a hospital stay — typically up to 100 days. Medicare does not pay for long-term custodial care at home or in a facility. Medicaid does pay for long-term care, but only after the person meets strict income and asset limits, and gifts made in the five years before applying can trigger a penalty period.
Can I get paid to care for a parent?
Sometimes. In many US states, Medicaid self-directed care programmes pay family members for home care. Some states also offer caregiver tax credits — Oklahoma's is up to $3,000 a year. The proposed federal Credit for Caring Act would offer up to $5,000, but it is not law yet, so there is nothing to claim.
What should I do if a parent suddenly starts giving money away?
Have a direct, calm conversation with all siblings present, ask what is driving the giving, and get a medical check — sudden changes can signal grief, depression or early cognitive decline. Then talk to an elder law attorney before anything else is transferred.
Key takeaways
- Family caregivers now spend an average of $11,508 a year out of pocket — up 59% in five years, and 31% of household income (76% under $40,000).
- Professional care is far higher: home aide $80,080 a year, assisted living $74,400, private nursing home room $129,575.
- Medicare does not pay for routine long-term care. Medicaid does, but only after a spend-down — and gifts within five years of applying can trigger a penalty period with no coverage.
- The proposed $5,000 Credit for Caring Act is not law. Claim what exists now: the Child and Dependent Care Credit, a dependent care FSA, an HSA, and state caregiver credits.
- Sudden large-scale giving by an aging parent deserves a calm family conversation, a medical check, and an elder law attorney.
The $11,508 figure is a warning, not a verdict. Families that plan spend less, fight less, and protect both the parent's dignity and the caregiver's future. The next step is a single conversation: ask your parent what care they would want, what money is available, and who should be authorised to act. Write the answers down.
Sources
- AARP — Caregiver Out-of-Pocket Spending Rises 59 Percent
- AARP — Family Caregivers' Out-of-Pocket Costs Jump Almost 60% in Five Years
- CareScout Cost of Care Survey 2025 — national medians
- NPR / WLIW — What's gone up even faster than gas or rent? The cost of caregiving
- Trualta — What Is the $5,000 Caregiver Tax Credit?
- Congress.gov — H.R. 2036, Credit for Caring Act of 2025
- The Ramsey Show — mother-in-law gave away $700,000–$1 million in savings
- Senior Safety Advice — How Much Is a Family Caregiver Worth?
The MoneyHabit editorial desk researches, writes and reviews every article against our editorial policy.
The Sunday Habit
One useful money idea, every week.
A short, practical email every Sunday — no spam, no selling your address, unsubscribe anytime.
Advertisement
More in Money News & Explainers
Money News & Explainers · Explainer
Your Parents' Wealth Matters More Than Your Salary
Family wealth now shapes who buys a home and retires comfortably: $124 trillion is set to change hands. What the inheritocracy means for your money.
17 November 2026 · 10 min read
Money News & Explainers · Explainer
Gen Z vs O'Leary: Is the System Really Rigged?
A viral Jubilee debate has Gen Z and Kevin O'Leary clashing over wages, debt and home prices. We graded the claims against the official data.
16 November 2026 · 10 min read
Money News & Explainers · Explainer
How Much Do Food Delivery Drivers Really Earn?
Two viral posts claim big delivery pay — £75 in a day, CAD 1,447 in a week. We checked the real numbers, the hidden costs, and what drivers actually keep.
9 November 2026 · 12 min read