Guide
Same Job, Same Raises. Why Only One Person Got Rich
A 3.2M-view video shows two people with identical raises — only one builds wealth. The fix: save half of every raise, automatically.
The video everyone is watching right now
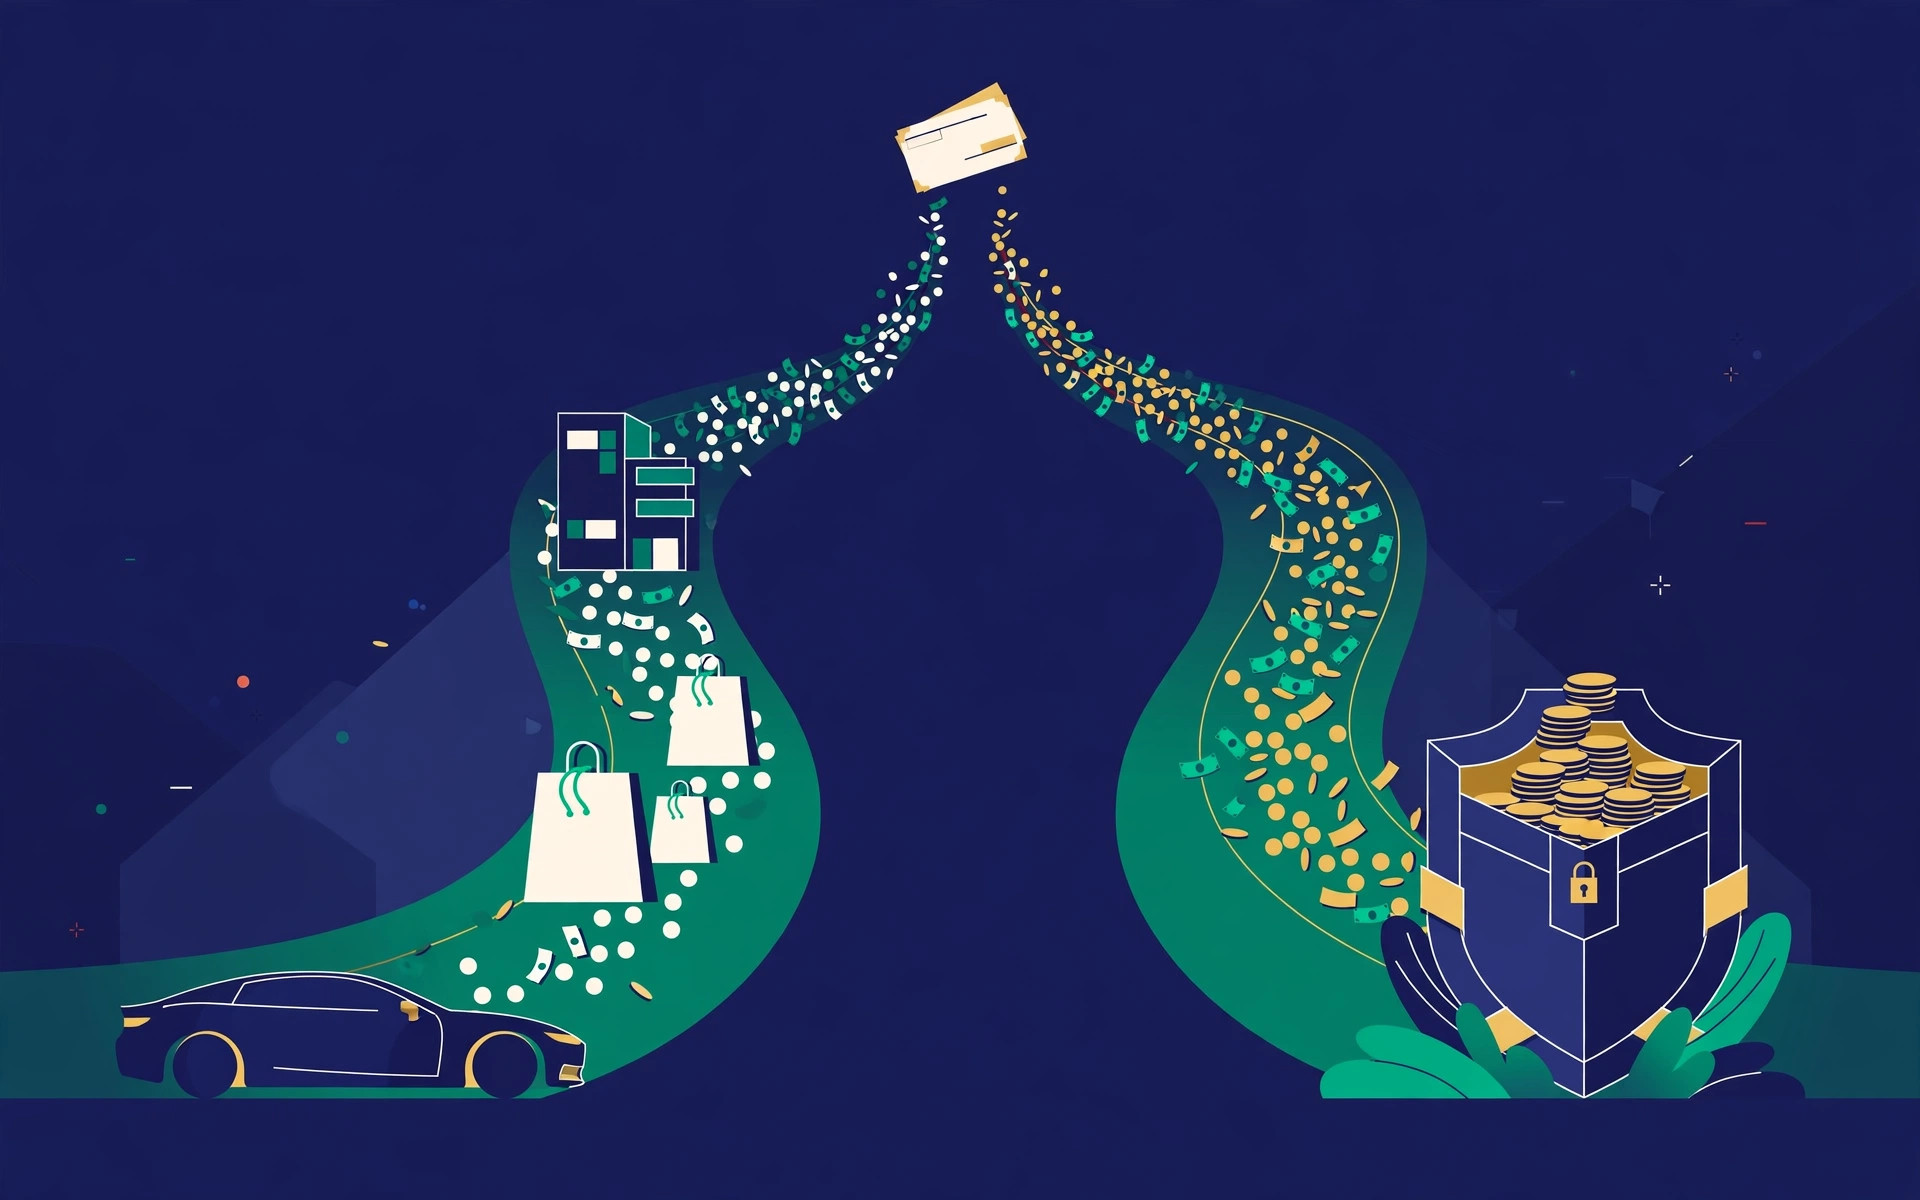
This week's most-watched personal finance video on TikTok is brutally simple. A creator shows two people with the same job, the same salary, the same raises — and eight years later, only one of them has a house. The clip has 3,193,384 views, 149,155 likes and 687 comments, topping the week's finance rankings well ahead of everything else. The message landing with millions of people is uncomfortable: your raises are not the problem. What you let them become is — lifestyle creep, the quiet process by which every pay increase gets absorbed until you earn far more and have no more to show for it.
Where raises actually go
Lifestyle creep almost never arrives as one big reckless purchase. It enters through small, individually reasonable upgrades:
- Housing: the renewal comes in, the spare-room flat is only a bit more, and "I can afford it now" does the rest. Rent rises every year; it almost never falls.
- Transport: the old car still runs, but the finance deal on something nicer is "only" £250/$300 a month — a three-year commitment disguised as a monthly number.
- Food and convenience: the delivery app remembers your card and reorders in one tap. Takeaway twice a month becomes twice a week.
- Subscriptions: the free trial converts silently, the premium tier is £3 more a month. Stack five of these and you have added £180/$200 a year without a single decision you would call spending.
None of these feels like a mistake. Together they form a ratchet: spending climbs to match income in weeks but refuses to fall back. You never decide to spend your raise — you just stop noticing it is gone.
Your raise did not disappear in one bad decision. It disappeared in forty good ones — each so reasonable you never argued with it.
The psychology: why more money rarely feels like more
In 1971, Philip Brickman and Donald Campbell coined the hedonic treadmill: as circumstances improve, expectations and desires rise in step, so we keep running yet stay roughly in the same emotional place.
The most famous test came in 1978, when Brickman, Dan Coates and Ronnie Janoff-Bulman compared major lottery winners with people who had become paraplegic after accidents. Against all intuition, the winners were not dramatically happier in everyday life, and the accident survivors adapted more than outsiders expected — the core insight that we adapt to new baselines fast, including financial ones, has held for decades.
That is the mechanism of lifestyle creep. The bigger flat thrills you for about a month, then becomes "just where you live." Every raise resets the treadmill to a slightly faster speed. Same effort, same view.
The math: what half your raise is actually worth
The fix is a system that captures the raise before the treadmill resets. Two people earn $70,000 with 3% raises for ten years, investing savings at 7%. Person A saves a flat $7,000 a year; every raise goes to lifestyle. Person B saves half of every raise on top of the $7,000 base.
| Year | Salary | A saves | B saves | B's invested total |
|---|---|---|---|---|
| 1 | $70,000 | $7,000 | $7,000 | $7,490 |
| 5 | $78,786 | $7,000 | $11,393 | $52,100 |
| 10 | $91,334 | $7,000 | $17,667 | $158,470 |
After ten years, A has $96,715 and B has $158,470 — a $61,755 gap — while B still enjoyed half of every raise. Same job. Same raises. Different system.
The half-raise rule: before your next raise arrives, decide that half of it is invisible — it goes to savings the day it lands. The other half is yours to enjoy, guilt-free. You never feel a cut, because you never had the money.
This has been tested in the real world
In 2004, Richard Thaler and Shlomo Benartzi published the results of the Save More Tomorrow program, which asked workers to commit in advance to raising their retirement contributions at each future pay rise. Participants' average savings rate rose from 3.5% to 13.6% over 40 months; 78% of those offered the plan joined, and around 80% stayed through four pay raises — because committing future income feels almost costless, while cutting current spending feels like a loss. The idea was influential enough to be built into US retirement law, making automatic contribution escalation standard in 401(k) plans after the Pension Protection Act of 2006.
You do not need a 401(k) to use the principle:
- Automate the capture. The day a raise is confirmed, raise your pension contribution, savings standing order or investment auto-transfer by half the raise. Do it before the first bigger paycheck lands.
- Let half through. Total austerity fails because it fights the treadmill head-on. The system only asks that the saved half moves first, automatically.
- Audit invisible subscriptions once. Cancel anything you would not sign up for today at full price. This is the one clean-up that compounds forever.
The credit trap: never fund lifestyle upgrades with debt. A raise is not a reason to carry a bigger balance — the card company will happily turn higher income into a higher limit, and the interest will eat the raise whole.
US/UK notes
In the US, check whether your 401(k) offers automatic contribution escalation — most plans added it after the 2006 Pension Protection Act. In the UK, workplace auto-enrolment has no built-in escalation, so set a reminder for every pay review and bump your pension percentage or standing order the same day.
Frequently asked questions
Does fighting lifestyle creep mean never enjoying a raise?
No — that is why the half-raise rule works. Letting half the raise through gives you the upgrades that genuinely improve your life while the automated half compounds quietly.
What if my raise barely covers inflation?
Apply the rule to the real increase, whatever it is. And if the raise is zero in real terms, protecting your existing savings rate is the victory that year.
A promotion changed my life — new commute, new wardrobe. Is that creep?
Some increases are the cost of the promotion itself. The test: would the expense exist if you were doing this job anyway? Fund genuine costs deliberately, and apply the half rule to what remains.
Should I save the whole raise instead?
If you can do it without resentment, sure. But the Save More Tomorrow results came from a gradual, painless design, not maximum austerity. Half is the rate almost anyone can hold for a decade — and a decade is what matters.
Key takeaways
- Lifestyle creep is structural, not a character flaw: small reasonable upgrades ratchet spending up to match every raise.
- The hedonic treadmill means new comforts stop feeling special within weeks — only the cost remains.
- Saving half of every raise is worth $61,755 more over ten years in a realistic example — while still enjoying half of each raise.
- Commit the increase before the bigger paycheck arrives, so you never feel a cut.
- Never finance the lifestyle first. Debt turns the ratchet into a lock.
Your next step
Before your next pay review, write one sentence: "Half of my next raise goes to savings the day it lands." Set the increase the same day the raise is confirmed. The treadmill runs either way — this rule just makes sure you keep some of the ground it covers.
Sources
- ContentScout — Finance TikTok performance data (Nov 3, 2026)
- Benartzi & Thaler (2004) — Save More Tomorrow, Journal of Political Economy (via Chicago Booth)
- US DOL CLEAR review — Save More Tomorrow study summary
- RePEc abstract — Save More Tomorrow: Using behavioral economics to increase employee saving
- The psychology of hedonic adaptation (Brickman & Campbell 1971; Brickman, Coates & Janoff-Bulman 1978)
More in Money Habits
Money Habits · Guide
Counting on an Inheritance? The Numbers Say Don't
Nearly 3 in 5 adults expecting an inheritance are planning their finances around it. Advisers call that a trap — here's how to make your plan inheritance-proof.
4 November 2026 · 6 min read
Money Habits · Guide
Money Manifestation Is Trending — Here's What Actually Works
Money manifestation is flooding social feeds this November. The ritual is fun, but psychology points to three habits that actually turn intentions into results.
3 November 2026 · 6 min read
Money Habits · Habit
The November Money Challenge: 30 Days of Small Money Wins
A viral November Challenge is sweeping feeds. Here's how to run a 30-day money challenge that survives December — backed by the real science of habits.
2 November 2026 · 8 min read