Guide
Earns ₹85,000, Invests ₹35,000 — and Had ₹3,200 Left
He put 41% of his ₹85,000 salary into SIPs — then a cracked laptop and an insurance bill left him borrowing ₹10,000 from a colleague.
In this article
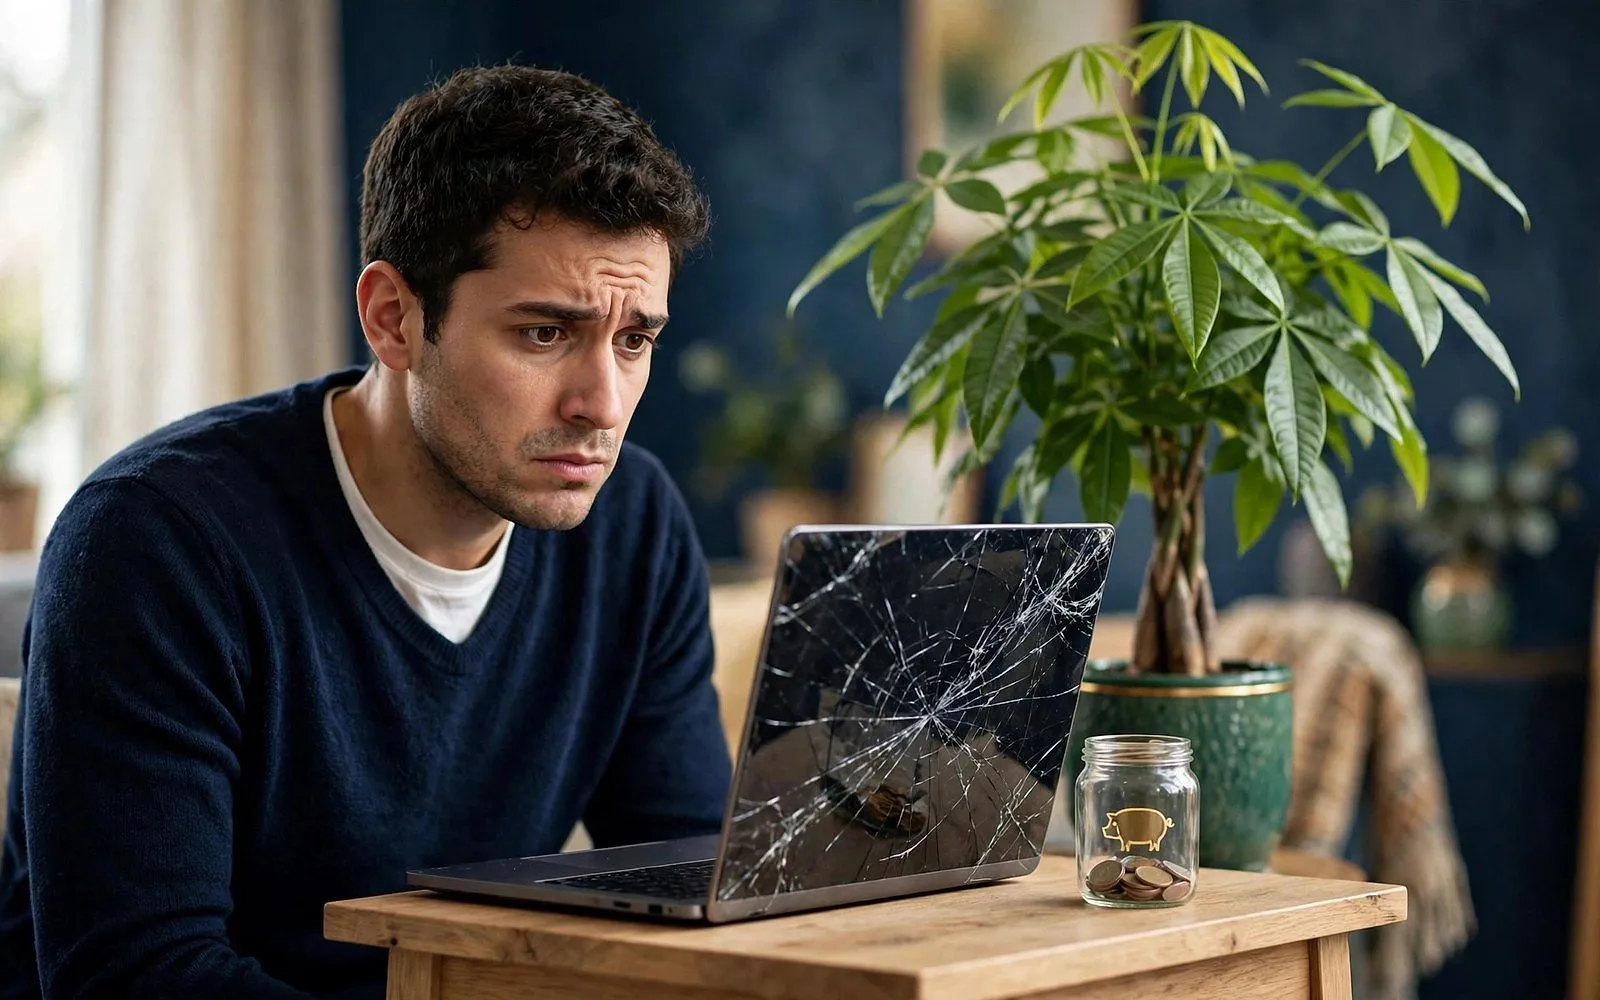
A 26-year-old in an Indian city earns ₹85,000 a month. Every month, he puts ₹35,000 of it into equity mutual funds through SIPs — a 41% savings rate most financial advisers would applaud. He felt proud of it. Then his laptop screen cracked. The repair cost ₹14,000. In the same week, his annual insurance premium of ₹11,000 came due. He opened his bank app and saw ₹3,200.
He had assets worth several lakhs. He had almost no money. So he borrowed ₹10,000 from a colleague.
His post on Reddit's r/IndiaFinance went viral this week, picked up by NDTV Profit on 3 November, because it punctures a comforting idea: that a high savings rate automatically means you are good with money. It doesn't. Where your money sits matters as much as how much of it you save — and this is the story of what happens when the order is wrong.
What actually happened
The numbers, as the poster shared them, are simple. Monthly salary: ₹85,000. Monthly SIP: ₹35,000. What was left covered rent, personal expenses, and money sent home to family. The rest of his wealth sat in fixed deposits and long-term investments — chosen for returns, not for availability.
Then two ordinary bills arrived in the same week: a ₹14,000 laptop repair and an ₹11,000 insurance renewal. Together, ₹25,000. Cash in the bank: ₹3,200. The gap was ₹21,800, and the only bridge he had was asking a colleague for ₹10,000.
Nothing here was reckless spending. There was no shopping spree, no loan for a holiday, no subscription pile-up. That is exactly why the story spread: the failure mode was invisible. He did the hard part — saving 41% of his income — and still ended up borrowing for a routine expense.
He did the hard part — saving 41% of his income — and still ended up borrowing for a routine expense. The savings rate was never the problem. The order was.
The mistake wasn't investing. It was the order.
The top-voted advice in the thread was blunt: "Build a 3-to-6-month emergency fund in a liquid account before locking money into equity SIPs." Another commenter put it even more plainly: keep some money in a savings account, and have a credit card for bigger expenses, since it gives a 30–45 day payment window.
They are describing the standard order of operations in personal finance, the sequence that turns a good savings rate into actual security:
- A small cash buffer first — enough to absorb one bad week (a repair, a bill, a missed payday).
- A full emergency fund next — typically 3–6 months of essential spending, in an account you can reach instantly.
- Then invest aggressively — SIPs, retirement accounts, long-term funds, with money you genuinely will not need for years.
The poster skipped steps one and two and went straight to step three. His 41% savings rate was real. It was also entirely locked away from the life it was supposed to protect.
Why "invested" money isn't "available" money
Part of the confusion is that a portfolio balance looks like money. It isn't — not on the day you need it. Every place you can park savings has a different price for getting it back in a hurry:
| Where the money sits | How fast you can spend it | What early access costs |
|---|---|---|
| Savings account | Instant | Nothing |
| Liquid / money-market fund | Usually 1 working day | None, but not instant |
| Equity mutual fund (SIP) | Typically 1–3 working days | Exit load ~1% if redeemed within a year; tax on gains; you sell at whatever the market is doing that day |
| Fixed deposit | Same day, but you must break it | Rate reset to the period actually held, minus a 0.5–1% penalty |
| ELSS tax-saving fund | Not available | 3-year lock-in per instalment — you cannot redeem at all |
That table is the whole story. Equity fund redemptions in India typically take 1–3 business days, and SEBI allows fund houses up to 10 working days. Redeem within the first year and most equity funds charge a ~1% exit load. And if the market is down the week your laptop breaks, you sell low — the worst possible timing, forced on you by a cracked screen.
Fixed deposits are no better as a buffer. Break a ₹1,00,000 FD booked at 7.5% for three years after just one year, and the bank pays the rate for the period actually held — say 6.5% — minus a penalty of around 1%. Your effective rate drops to about 5.5%. On ₹1,00,000 for a year, that is ₹2,000 of interest gone, for the privilege of using your own money. (These are illustrative figures using typical bank terms; SBI charges 0.5% on deposits up to ₹5 lakh and 1% above, HDFC Bank typically 1%.)
The trap: money in investments and FDs still counts in your net worth — but net worth doesn't pay a repair bill. Only cash you can reach today does. If every rupee is working for returns, none of it is working for emergencies.
What the ₹25,000 week actually cost him
The financial cost of that week was small. The real costs were elsewhere:
- ₹21,800 short on a ₹25,000 bill, with ₹3,200 in the bank.
- A loan from a colleague — ₹10,000 borrowed at work, with all the awkwardness that carries, despite owning assets worth several lakhs.
- The forced choice he avoided: redeeming SIP units at whatever the market offered that day, or breaking an FD and paying the penalty. Either way, an ordinary bill would have eaten into long-term wealth.
And the irony: his SIPs were doing their job. ₹35,000 a month for a year at an assumed 12% annual return grows to roughly ₹4,43,900 against ₹4,20,000 invested — a gain of about ₹23,900 (illustration only; real returns vary and are never guaranteed). The investments weren't the problem. The missing ₹25,000 of accessible cash was.
The fix: build the buffer first, then invest hard
The correction isn't "stop investing." It's a pause with a deadline. Two routes, same destination:
| Route | What changes | Result |
|---|---|---|
| Pause and build | Redirect the full ₹35,000 SIP for 3 months into a savings account | ₹1,05,000 cash buffer, then restart SIPs at full speed |
| Split and build | ₹20,000 to SIPs + ₹15,000 to the buffer each month for 6 months | ₹90,000 buffer and ₹1,20,000 still invested — no investing gap at all |
The split route is usually the easier one to stick to, because it never asks you to stop a habit you are proud of. The pause route is faster. Either beats the position he was in: three months of discipline buys a buffer that ends the borrowing forever.
How big should the buffer be? The standard guidance is 3–6 months of essential spending — not income, spending. If your essentials run ₹50,000 a month, that is ₹1,50,000 to ₹3,00,000. That sounds like a lot until you compare it with what it replaces: the colleague loan, the broken FD, the forced sale. Start with one month. One month of essentials in a savings account already covers the exact week that broke this budget.
Do this first: before your next SIP date, move one month of essential spending into a separate savings account — ideally a different bank from your spending account, so you see it but don't spend it. Then set a standing instruction to add to it every payday until it covers three months. Only then raise your SIP back up.
The same trap, in the US and UK
This isn't an India-only mistake. The mechanics are identical everywhere; only the account names change.
- United States: maxing a 401(k) while holding $0 in savings is the same error in a different wrapper — and early 401(k) withdrawals add a 10% penalty plus income tax on top. The fix is the same: a high-yield savings account first (top rates are around 4–5% APY), then retirement contributions.
- United Kingdom: the same logic applies to Stocks & Shares ISAs and pensions. Easy-access savings first, then the ISA — and remember pension money is locked until at least age 57, so it can never be your emergency fund.
- Everywhere: a credit card can bridge a gap — the 30–45 day interest-free window commenters mentioned is real — but only if the balance is cleared in full. A card used as an emergency fund that isn't repaid becomes the most expensive loan you own.
Frequently asked questions
Should I stop my SIP to build an emergency fund?
Pause it or shrink it — don't cancel the habit. A 3-month pause or a 6-month split (as in the table above) builds a real buffer, and you restart with the same discipline intact. What you should not do is keep investing 41% while your bank balance sits at ₹3,200.
Is a 41% savings rate too much?
No — it's impressive, and it isn't the problem. The problem is that 100% of the saving went into illiquid places. A 41% rate split as, say, 30% investing and 11% buffer-building for a few months is still a 41% rate, and it actually survives contact with real life.
Can't I just redeem mutual funds when I need cash?
You can, but you pay for the privilege: 1–3 working days' wait, a possible ~1% exit load in year one, tax on gains, and the risk of selling during a market dip. For a planned expense you can wait; for a cracked laptop on a Monday, three days is a long time. That's what the liquid buffer is for.
How much cash is "enough" before I invest?
One month of essentials is the minimum that changes your life — it covers the surprise bill without borrowing. Three months is the standard target, six if your income is irregular or you're the sole earner. Build it in a savings account or liquid fund, not in equities.
Key takeaways
- A 41% savings rate didn't save this investor from borrowing ₹10,000 — because none of it was reachable cash.
- Invested money isn't available money: equity funds take 1–3 working days to redeem, FDs cost a 0.5–1% penalty to break, ELSS funds are locked for 3 years.
- The order is buffer first, then investing: one month of essentials, then three, then six — then invest as aggressively as you like.
- A 3-month SIP pause or a 6-month split builds a ₹90,000–₹1,05,000 buffer without killing the investing habit.
- The same trap exists in the US and UK: retirement accounts and ISAs are not emergency funds.
The poster's story went viral because millions of people recognised themselves in it — diligent, disciplined, and one cracked laptop away from borrowing. The fix is unglamorous and takes about three months. This week, check your own numbers: if your bank balance couldn't cover a ₹25,000 surprise, your next payday's first job isn't the SIP. It's the buffer.
Sources
The MoneyHabit editorial desk researches, writes and reviews every article against our editorial policy.
The Sunday Habit
One useful money idea, every week.
A short, practical email every Sunday — no spam, no selling your address, unsubscribe anytime.
Advertisement
More in Financial Literacy
Financial Literacy · Explainer
She Turned Down $1M for $1,000 a Week: Was She Right?
A 20-year-old turned down $1 million for $1,000 a week for life — and the internet erupted. We ran the numbers on who was right.
19 November 2026 · 10 min read
Financial Literacy · Explainer
How Long Will $300,000 Last in Retirement?
A viral reel says $300,000 can fund retirement at 4.7% a year. We ran the numbers — dividends, Social Security, bad markets — to see how long it really lasts.
19 November 2026 · 10 min read

Financial Literacy · Explainer
Cash ISA U-Turn Explained: Your £20,000 Allowance Stays
The planned cash ISA cut is scrapped: your £20,000 allowance stays. Here is what changes on savings tax, what the new starter ISA means, and what to do next.
29 October 2026 · 7 min read