Guide
Cash Stuffing Is Viral Again: Does It Actually Work?
Cash stuffing is all over TikTok again. Here's how the envelope budget really works, what it costs you, and a hybrid setup for a digital world.
By MoneyHabit Editorial Team · 19 October 2026 · 6 min read
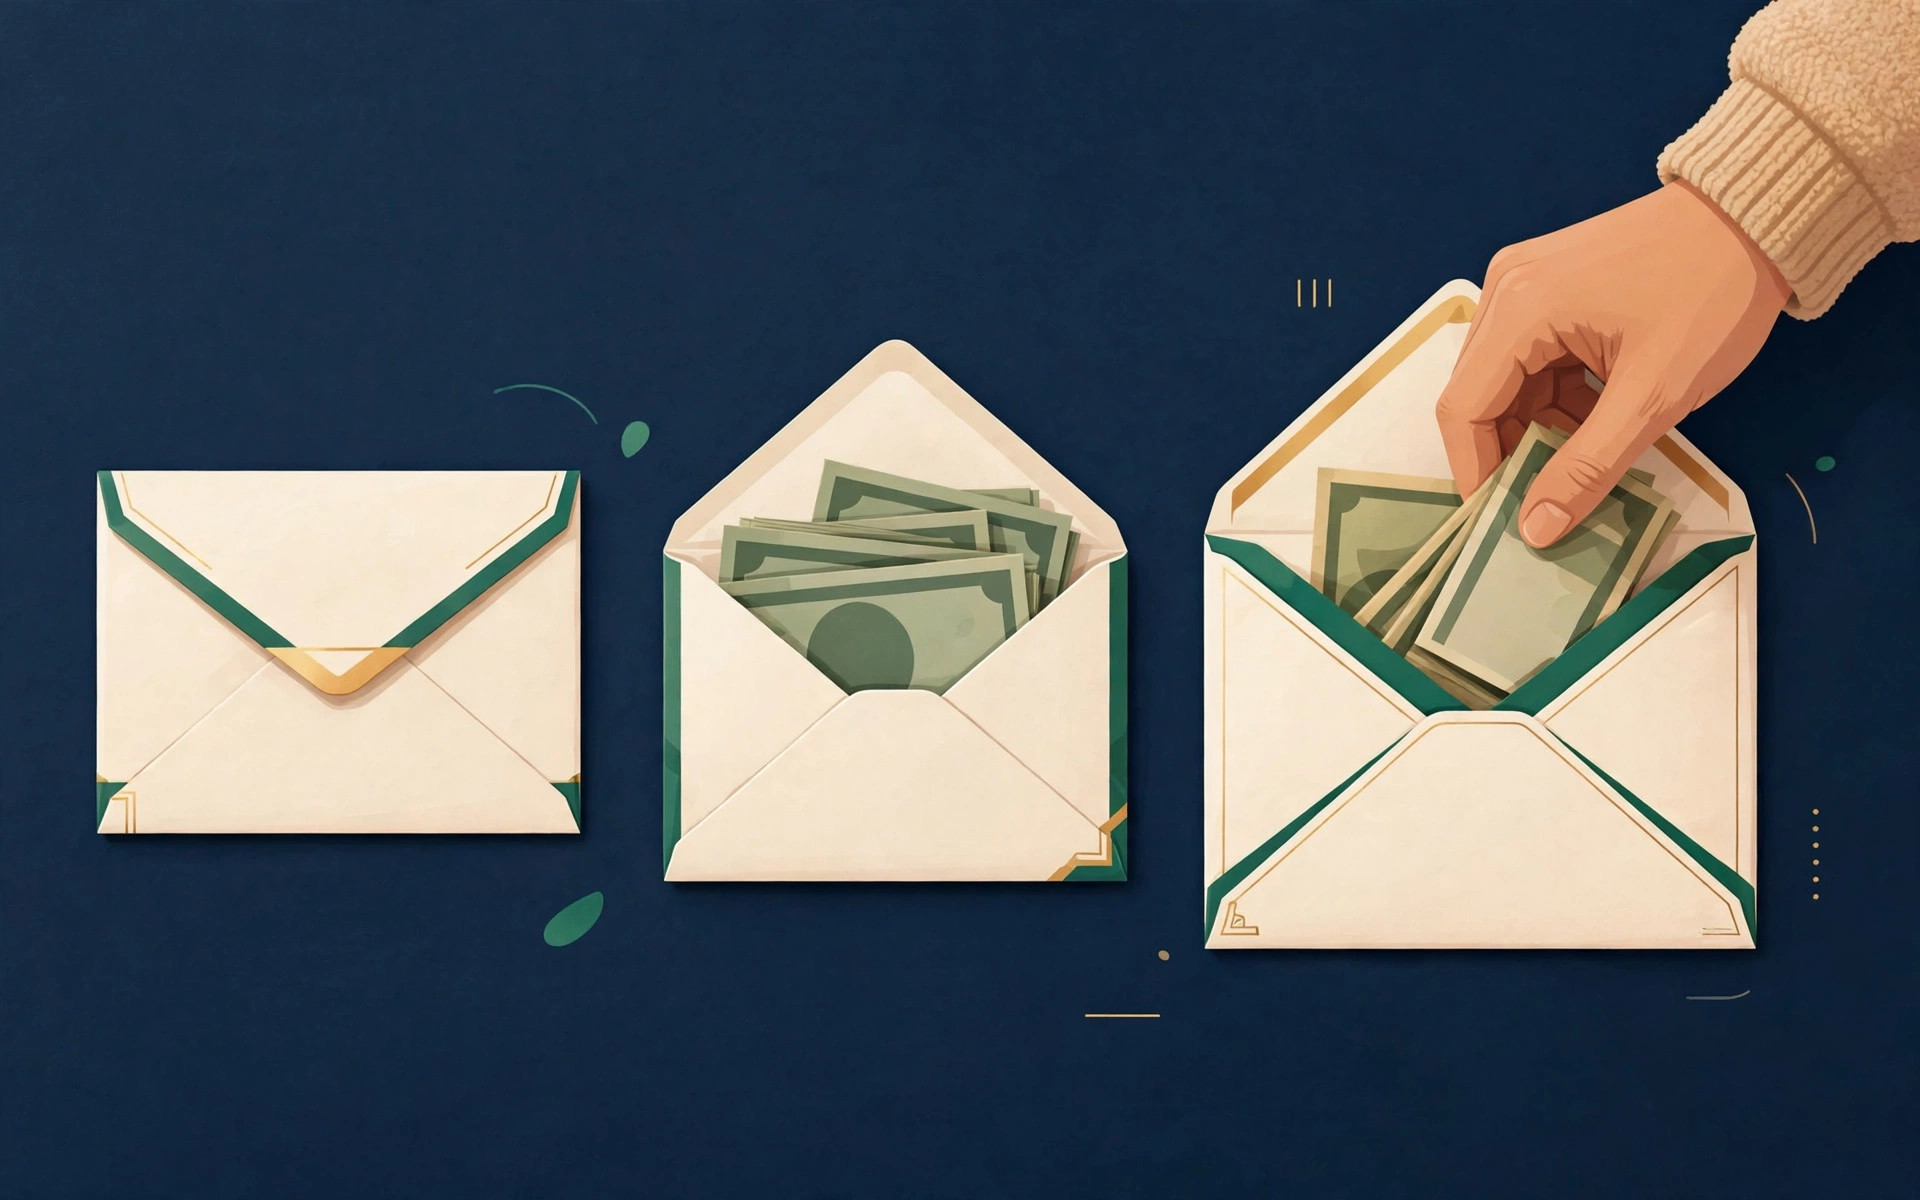
Cash stuffing — the decades-old envelope budget dressed up as content — is having another massive viral moment: videos tagged #cashstuffing and #cashenvelopes have racked up billions of views, and October 2026 roundups rank it among the defining money trends of the month. Before you buy a binder, it's worth asking: genuine budgeting breakthrough, or something that just films well?
What cash stuffing actually is
Strip away the washi tape and the aesthetic binders and the method is almost brutally simple. Each pay cycle, you withdraw the part of your paycheck that covers flexible spending — groceries, fuel, dining out, entertainment, personal spending — in cash. You divide it into labeled envelopes, one per category, and spend only from the matching envelope. When an envelope is empty, spending in that category stops until the next payday. Bills that must be paid electronically — rent, utilities, loan payments — stay on autopilot in your bank account.
That's the whole system. No app to configure, no subscription, no algorithm. It's a physical version of a rule finance writers have repeated for decades: give every dollar a job before you spend it, and make the boundary between "budgeted" and "overspent" something you can feel.
Why it's blowing up right now
The backdrop is grim reading: the Federal Reserve's 2025 Survey of Household Economics found that only 63% of U.S. adults could cover a surprise $400 expense with cash — down from 68% in 2021 — and PYMNTS Intelligence reported 68% of Americans living paycheck to paycheck as of August 2025.
When margins are that thin, the appeal of a system that makes overspending physically impossible is easy to understand. A spending alert in a banking app is a suggestion you can dismiss; an empty envelope is a wall. The real value is the half-second pause when you open an envelope and see nothing in it — apps never create that pause, because there's no physical barrier between you and the transaction.
The whole system works on one insight: a number on a screen never stopped a purchase. An empty envelope does.
How to set it up in one afternoon
Start small and contain the experiment to flexible categories only:
- Pick 4–6 flexible categories. Groceries, dining out, fuel, personal spending, and a "fun money" envelope. Keep fixed bills out.
- Set amounts from reality. Use your last three months of actual spending, not aspirational numbers.
- Withdraw on payday. Take the total in one trip, divide it immediately, keep the envelopes in one place.
- One rule: spend from the right envelope. Empty dining envelope on the 20th? You cook.
- Review next payday. Which envelopes emptied early, which had leftovers — that's your calibration data.
Example split for $1,200 of flexible spending per two weeks:
| Envelope | Per two weeks | Covers |
|---|---|---|
| Groceries | $350 | Supermarket runs, household basics |
| Dining out | $100 | Restaurants, takeout, coffee |
| Fuel / transport | $120 | Gas, tolls, parking |
| Personal | $80 | Clothing, haircuts, small wants |
| Fun money | $50 | Zero-guilt spending |
| Total | $700 | Remainder stays in the bank for fixed bills |
Adjust the numbers to your own costs — the structure is what matters, not the figures.
Tip: The first month is diagnostic, not judgmental. Run cash stuffing for one pay cycle purely to discover where your money leaks — then keep, adjust, or abandon it based on what the envelopes tell you.
What the viral videos don't mention
Critics make three fair points:
- Cash in envelopes earns nothing. Every dollar in a binder earns zero interest. For small discretionary envelopes the loss is trivial; for people stuffing thousands, it adds up.
- Cash can be lost or stolen. Money in a bank account is insured; money in an envelope on the kitchen counter is not.
- The digital world doesn't take envelopes. Subscriptions, online orders, card-based transit, parking apps — a cash-only approach doesn't cover modern spending. One reviewer's verdict: it works well, but it's impractical in a digital-first world of card-based and contactless payments.
Warning: Don't withdraw rent, bill, or emergency-fund money as cash for stuffing. Keep fixed obligations and savings in the bank — envelope budgeting is for flexible spending only. And keep receipts: cash leaves no paper trail unless you make one.
Cash stuffing vs. digital envelope budgeting
| Cash stuffing | Digital envelope budgeting | |
|---|---|---|
| Overspending brake | Hard: the cash runs out | Soft: an alert you can dismiss |
| Tracks card and online spending | No | Yes, automatically |
| Interest earned | None | Full account rate |
| Theft / loss risk | Yes, uninsured | No, bank-insured |
| Setup effort | Low: label, stuff, go | Medium: link accounts, build categories |
| Best at | Stopping flexible-category overspending | Showing the whole financial picture |
Nobody wins every row, which is why the current consensus keeps landing on a hybrid: cash for the categories that leak, digital for everything else. Put your two or three worst leaks — groceries and dining out are the classics — in cash envelopes, and run bills, savings, subscriptions, and online spending through your bank or a budgeting app.
US vs. UK notes
In the US, money in an FDIC-insured bank account is protected; cash in an envelope is not, and cash at home is typically not covered by homeowners insurance either. In the UK, bank deposits carry FSCS protection (up to £85,000 per institution) — and purchases over £100 on a credit card are protected under Section 75 of the Consumer Credit Act, which cash can't offer. The hybrid approach sidesteps this: envelope the everyday leaks, keep larger purchases on cards.
Frequently asked questions
Is cash stuffing just for people who are bad with money?
No — it's for people whose problem is behavioral, not mathematical. If you know your numbers but keep overriding them, a physical boundary targets exactly that failure mode.
Doesn't it mean losing credit card rewards?
For enveloped categories, yes — that's the honest price of the friction. If rewards earn you 2% but envelopes cut your dining spend by 20%, the envelopes win by a mile. Rewards only beat discipline if the discipline already exists.
What if I'm already mostly cashless?
Try digital envelope budgeting: many banks and apps let you create separate "spaces" or "pockets" per category, some with their own virtual cards. You keep the discipline, the interest, and automatic tracking — at the cost of a softer spending brake.
How long should I try it before deciding?
Two full pay cycles. The first is calibration (your amounts will be wrong); the second is the real test. Even if you quit, you walk away with two cycles of spending data — valuable intelligence for whatever system you use next.
Key takeaways
- Cash stuffing is the classic envelope budget, gone viral: withdraw your flexible spending in cash, divide it into labeled envelopes, and stop when an envelope is empty.
- It works because the friction is physical — an empty envelope stops a purchase in a way a dismissible app alert cannot.
- The honest costs: cash earns no interest, it's uninsured against theft or loss, and it can't cover card-based or online spending.
- The consensus approach is hybrid: cash envelopes for the categories where you leak money, digital for bills, savings, and online spending.
- Start with one pay cycle and only flexible categories — treat the first month as a diagnostic, not a verdict.
So does cash stuffing actually work? For its real job — stopping overspending in flexible categories — yes: commit your spending while you're rational, and make the boundary physical. It won't replace a budget and it won't build wealth. But if apps haven't stopped you swiping past your own limits, the humble envelope might be the one trend worth borrowing. Start this Friday, with one category, and see what the envelopes teach you.
Sources
- Wisest Wallet — Cash Stuffing vs. Digital Envelope Budgeting in 2026
- SavingAdvice — 12 Viral TikTok Tips Tested
- FinanceBuzz — 5 TikTok Financial Trends That Are a Total Waste of Money
- Smart Cents Club — Cash Stuffing vs. Digital Budgeting: Why Hybrid Might Win
- Blackcat — Cash Stuffing in 2026: How TikTok's Favourite Budget Method Looks on a Phone
More in Budgeting & Saving
Budgeting & Saving · Guide
October's Bonus Paycheck: How to Use Your Third Check
October 2026 has five Fridays, so some biweekly workers get a third paycheck on Oct 30. Here's how to check your schedule and put the bonus check to work.
18 October 2026 · 7 min read
Budgeting & Saving · Guide
How to build an emergency fund on a tight budget
You don't need three months of expenses saved before an emergency fund helps. Here's a step-by-step plan to build your first $500–$1,000 safety net on a tight budget — and grow it from there.
17 October 2026 · 10 min read
Budgeting & Saving · Guide
The 50/30/20 budget rule, explained with examples
Split your take-home pay into 50% needs, 30% wants and 20% savings — the simplest budgeting framework that actually works, plus when to bend it.
17 October 2026 · 6 min read