Guide
3 Money Rules for Kids: Invest 70%, Spend 30%
Ankur Warikoo's viral reel sets three money rules for kids: buy because you need it, spend freely on learning, and invest 70% of gift money.
In this article
- The three rules, as posted
- Why age seven keeps coming up
- Rule 1: "Why buy it?" — the question that does the parenting
- Rule 2: No budget for books, learning and experiences
- Rule 3: Invest 70%, spend 30% — and the maths behind it
- Where the 70% actually goes
- Making the three rules stick
- Frequently asked questions
- Key takeaways
A short reel posted on 21 November 2026 has parents sharing it in the comments — for once, in a good way. In it, finance creator Ankur Warikoo and his wife lay out three money rules for their kids, simple enough for a seven-year-old to repeat. The third one does most of the work: of every birthday or festival gift, invest 70% and spend 30%. Viewers are already describing how they run the same split with their own children.
Here is what the rules are, the research behind why starting early matters, the maths on what 70% becomes, and where that money should live in the US and the UK.
The three rules, as posted
Rule 1: Don't buy something because your friends have it. Buy it because you need it. Before any purchase, the child has to answer one question: "Why buy it?" If the honest answer is "because my friend has one," the answer is no.
Rule 2: Books, learning and experiences have no budget — unlimited money. Anything that builds knowledge or creates a memory is exempt from the usual limits. The family spends freely on reading, courses, trips and experiences.
Rule 3: Money from birthdays and festivals gets split — invest 70%, spend 30%. Gift money is not pocket money. Most of it goes to work; a smaller slice is the child's to enjoy now. When the kids ask why, the parents' answer is: "You'll know in 15 years."
Why age seven keeps coming up
A 2013 research review by Dr David Whitebread and Dr Sue Bingham of the University of Cambridge, commissioned by the UK's Money Advice Service, found that the foundations of adult money habits are laid early. By around age seven, most children can recognise the value of money, understand that money is exchanged for goods, and have a working idea of earning and income. They can also plan ahead, delay a decision, and understand that some choices are irreversible.
Two details matter here. First, children under eight have not yet developed an understanding of the difference between luxuries and necessities — which is exactly why Rule 1 exists. A child who cannot yet tell a want from a need needs the question asked out loud, every time, until the habit forms. Second, the review concluded that teaching young children explicit financial facts is likely to be ineffectual in shaping their behaviour. What shapes it is modelling: children pick up their attitudes to money by watching how the adults around them handle it.
By seven, most children can plan ahead and delay a decision — but they still can't tell a luxury from a necessity. That gap is the whole job of parenting around money.
That is also why the popular shorthand — "money habits are set by seven" — needs a correction. The review describes foundations forming early, not a deadline. A nine-year-old or a fourteen-year-old is not too late. Start where your child is.
Rule 1: "Why buy it?" — the question that does the parenting
Peer pressure is the most expensive force in a child's financial life, and it arrives years before they have any income of their own. A classmate's new trainers, a YouTuber's unboxing, a limited-edition toy that "everyone" has — each one tests whether your child can separate wanting from needing.
Rule 1 does not ban wanting. It forces a reason. "Why buy it?" has only a few acceptable answers at this age: it replaces something broken, it is needed for school or a hobby, or it will genuinely be used often. "Because my friend has it" fails the test — and the child learns to say so themselves rather than hearing a parental "no" they resent.
Make the rule visible: ask the question back and wait. The first dozen times, your child will struggle. By the twentieth, many start asking themselves before they ask you — which is the entire point.
Try it as a game first: for one week, every family purchase — including yours — has to pass the "why buy it?" question out loud. Children copy what they see far more reliably than what they are told.
Rule 2: No budget for books, learning and experiences
This is the rule most parents get backwards. We haggle over a £10 book while spending £60 on a toy that is forgotten by February, then wonder why our children value things over learning. Warikoo's second rule flips the priority on purpose: the categories that compound — reading, skills, travel, time together — are the ones with no spending cap.
"No budget" does not mean "no judgement." It means these categories are never the first thing cut when money is tight, and a child never has to argue for a book the way they argue for a game. A child who grows up watching books arrive without a negotiation learns that learning is a default, not a luxury to be earned.
Rule 3: Invest 70%, spend 30% — and the maths behind it
This is the rule the comments are arguing about, and the one that does the long-term work. Every gift of cash — birthday money from grandparents, festival money, a cheque from an aunt — gets split the moment it arrives: 70% invested, 30% for the child to spend now. The 30% is not a concession; it is the reason the rule survives. A child who never gets to enjoy any of their money learns that saving means deprivation. The 30% teaches spending as a skill — choosing, waiting, enjoying — while the 70% quietly builds the pot.
Here is what the 70% becomes. These are illustrations at a steady 7% annual return, not predictions — real returns vary, and no investment guarantees 7%:
| Scenario | Invested over time | Value at age 18* |
|---|---|---|
| One $100 gift at age 3, $70 invested | $70 once | $193 |
| $200 of gift money a year, ages 5–18 | $1,820 | $3,017 |
| $500 of gift money a year, ages 5–18 | $4,550 | $7,543 |
| $1,000 invested at birth | $1,000 once | $3,380 |
*Own arithmetic, labelled as illustration: 7% annual return, compounded yearly. The $200-a-year example assumes $140 invested each year from age 5 to 18.
The numbers are modest, and that is the honest point. A 70/30 split on birthday money will not make a child rich. What it makes is a teenager who has watched money grow for a decade and arrives at adulthood with an investing habit already installed. The pot matters less than the person it builds.
Do not invest money your child needs soon. Gift money earmarked for a school trip, a bike, or a near-term goal should stay in cash. The 70% rule applies to money with a decade or more to grow — that is where investing earns its keep.
Where the 70% actually goes
A rule is only as good as its account. In the US, the standard vehicle is a custodial brokerage account — a UGMA or UTMA account. An adult opens and manages it, but the assets legally belong to the child, and the custodian can only use the money for the child's benefit. Control transfers to the child at the age of majority under state law, typically 18 or 21, and up to 25 in some states. Contributions are irrevocable gifts: once the money goes in, it cannot be taken back. In 2026, gifts of up to $19,000 per recipient per year fall under the annual gift-tax exclusion.
Two warnings before you open one. First, the child gets full, unrestricted control at the transfer age — no conditions can be attached. Second, custodial assets count as the student's own assets for college financial aid, and student-owned assets are assessed far more heavily than parent-owned assets. If college aid matters, a 529 plan may be the better home for education money: contributions grow tax-free and withdrawals are tax-free for qualified education expenses, including up to $20,000 a year for K-12 costs from 2026. A 529 stays under the account owner's control — the child is the beneficiary, not the owner.
There is also tax to mind. Under the 2026 "kiddie tax" rules, the first $1,350 of a child's unearned income is untaxed, the next $1,350 is taxed at the child's own rate, and anything above $2,700 is taxed at the parents' marginal rate.
| Account | Who controls it | Best for | Watch out for |
|---|---|---|---|
| Custodial (UTMA/UGMA), US | Child, at 18–21 (up to 25) | Flexible gift-money investing | Irrevocable; full control at majority |
| 529 plan, US | Account owner, indefinitely | Education savings, tax-free growth | Non-qualified withdrawals taxed plus 10% penalty on earnings |
| Junior ISA, UK | Child, at 18 | Tax-free saving/investing to £9,000 a year (2026/27) | Locked until 18; child takes full control then |
In the UK, the equivalent is a Junior ISA: up to £9,000 tax-free in the 2026/27 tax year, split between a cash Junior ISA and a stocks and shares Junior ISA, locked away until the child's 18th birthday. Anyone can contribute once the account is open. The same control warning applies: at 18, it is the child's money, with no strings attached.
Outside the US and UK, the principle travels even where the account names do not: look for your country's child investment or education account, and check whether contributions are irrevocable, who controls the money and when, and what the tax treatment is before you open anything.
Making the three rules stick
Rules fail when they are invisible. These three survive because they are easy to see and easy to repeat:
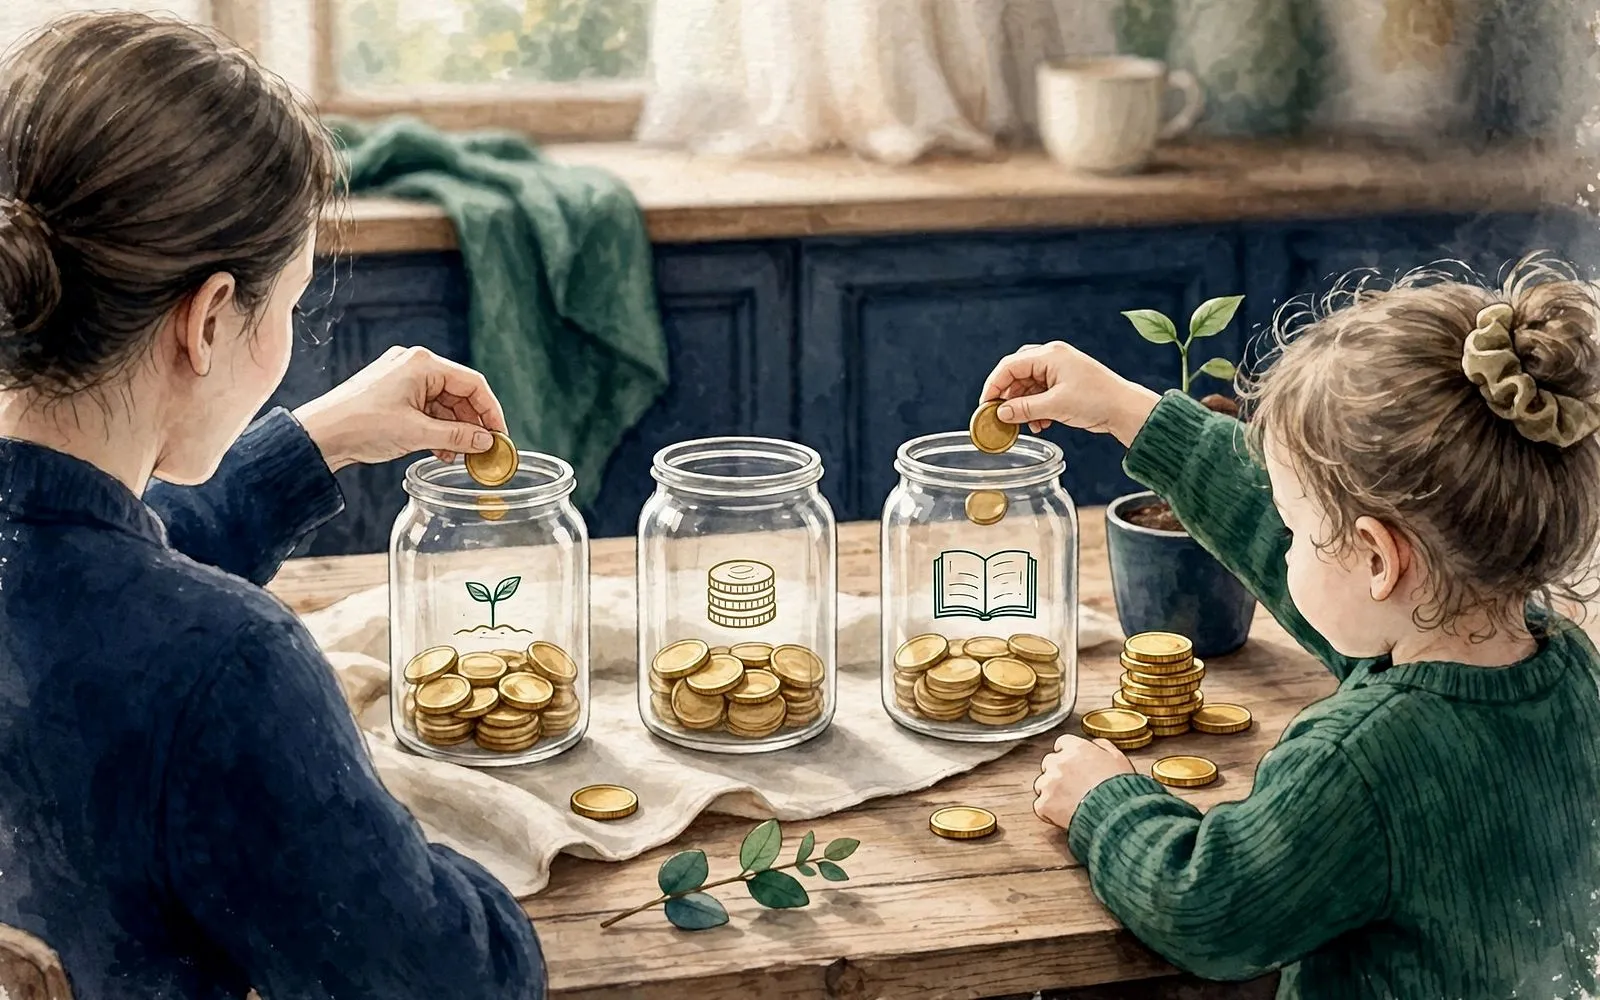
- Use three jars or envelopes. Label them Invest, Spend, and Learn. Birthday money gets physically split in front of your child, 70/30, every time. The ritual is the teaching.
- Show the growth. Once a year, on the child's birthday, open the investment account together and look at the balance. A pot that grows beats a lecture about compounding.
- Let the 30% be spent badly sometimes. A toy that breaks in a week is a cheap lesson when the stakes are $30 of birthday money. It is an expensive lesson at thirty, with a salary.
Frequently asked questions
What age should we start the 70/30 split?
As soon as your child receives gift money they can understand — usually around five or six. Younger children can still watch the split happen; the ritual teaches before the maths does.
Is 70% too much to invest for a child?
It is a rule of thumb, not a law. If gifts are small, 70% of very little is still very little — the habit is the point, not the amount. If your child has a genuine near-term need, spend the money. Some families use 50/50 for younger children and move to 70/30 as they get older.
Do I need a custodial account for small amounts of gift money?
Not at first. For small sums, a simple savings account in the child's name — or even the labelled jars — is enough while the habit forms. Open a custodial account or Junior ISA once the pot is big enough to justify investing.
What if my child hates the rules and just wants to spend everything?
That is normal, and it is the reason the 30% exists. Let them spend their slice freely — the disappointment of a bad purchase teaches faster than any lecture. Keep the 70% non-negotiable but let them see it grow each year.
Key takeaways
- Ankur Warikoo's viral 21 November reel sets three rules for kids: buy because you need it, spend freely on learning and experiences, and invest 70% of gift money while spending 30%.
- Cambridge research finds the foundations of money habits form before age seven — and parental example shapes behaviour more than formal lessons.
- The 70% compounds: $140 invested a year from age 5 to 18 becomes about $3,017 at a steady 7% return, on $1,820 contributed — the habit matters more than the amount.
- In the US, a custodial UTMA/UGMA account or a 529 plan holds the 70%; in the UK, a Junior ISA up to £9,000 a year in 2026/27. All hand full control to the child at 18–21, so know the trade-offs before you open one.
- Make the rules visible: three jars and a yearly look at the balance turn rules into habits.
The reel's best line is the throwaway one: "You'll know in 15 years." A child who spends their birthday money today forgets it by next week. A child who invests 70% of it, year after year, opens an account at eighteen and finds several thousand dollars — and a habit — waiting. Start with the next birthday.
Sources
- Ankur Warikoo — 3 money rules for kids (Instagram reel, 21 Nov 2026)
- Ankur Warikoo — 3 money rules for kids (Facebook reel, 21 Nov 2026)
- NerdWallet — UTMA & UGMA Custodial Accounts
- J.P. Morgan — What Is a Custodial Account?
- TurboTax — 529 Plans and Taxes
- MoneyHelper — Junior ISAs
- Whitebread & Bingham (Cambridge) — Habit Formation and Learning in Young Children, Money Advice Service 2013
The MoneyHabit editorial desk researches, writes and reviews every article against our editorial policy.
The Sunday Habit
One useful money idea, every week.
A short, practical email every Sunday — no spam, no selling your address, unsubscribe anytime.
Advertisement
More in Financial Literacy
Financial Literacy · Guide
Wrong Money in Your Account? Why You Can’t Keep It
A lawyer just returned ₹34 crore sent to him by mistake. Here’s what the law says in the US, UK and India — and what to do if it happens to you.
19 November 2026 · 11 min read
Financial Literacy · Explainer
What Is a Money Market Fund? The Plain-English Guide
Money market funds pay close to 3.9% while the average savings account pays 0.38%. What they are, how they differ from savings accounts, and the risks to know.
18 November 2026 · 10 min read

Financial Literacy · Guide
The Employer Match: Free Money Most Workers Miss
One in four workers misses part of their employer match — about $1,336 a year. Here is how the match works, and the 10-minute check that captures it.
16 November 2026 · 10 min read